Seeing ₦100,000 in your bank account can make you feel like you have ₦100,000 available to spend.
But that may not be true.
Part of the money could already be needed for rent, school fees, a business payment, an upcoming bill, savings or another financial responsibility.
This creates what we can call the bank balance trap: confusing your total account balance with the amount of money you can safely spend.
In this guide, NaijaMoneyGuide explains a simple way to calculate your real spendable balance before making purchases.
What Is the Bank Balance Trap?
Your bank balance tells you how much money is currently in your account.
It does not necessarily tell you how much money is available for discretionary spending.
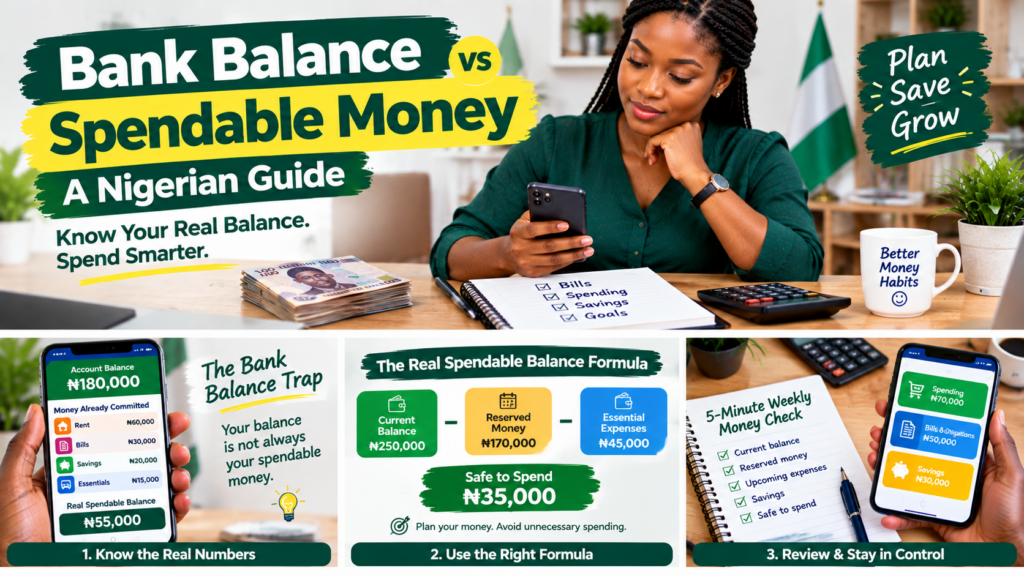
For example, suppose your account shows:
₦180,000
You may feel comfortable spending ₦20,000 on something you want.
But imagine that you have already planned:
- ₦60,000 for rent
- ₦30,000 for an upcoming bill
- ₦20,000 for savings
- ₦15,000 for transportation and food
That means a large portion of the ₦180,000 already has a purpose.
Your real flexible balance is much lower.
The Real Spendable Balance Formula
A simple way to think about your money is:
Real Spendable Balance = Current Balance − Reserved Money − Upcoming Essential Expenses
For example:
Current balance: ₦180,000
Reserved for rent: ₦60,000
Reserved for bills: ₦30,000
Planned savings: ₦20,000
Essential upcoming spending: ₦15,000
Therefore:
₦180,000 − ₦60,000 − ₦30,000 − ₦20,000 − ₦15,000 = ₦55,000
Your account still displays ₦180,000.
But your flexible money is approximately ₦55,000 based on this plan.
That is a much more useful number when deciding whether you can afford an optional purchase.
Step 1: Start With Your Current Balance
Open your banking app or check your latest account balance.
Write down the amount.
For example:
Current balance: ₦250,000
Do not immediately treat this entire amount as spendable.
This is only your starting point.
Step 2: Remove Money That Already Has a Job
Ask:
“What money in this account already belongs to something else?”
Examples include:
- Rent
- School expenses
- Utility bills
- Business expenses
- Planned savings
- Family commitments
- Debt repayments
- Upcoming travel
- Other known obligations
Write these amounts down.
Example
Current balance: ₦250,000
Rent: ₦80,000
Business expense: ₦40,000
Savings: ₦30,000
Bills: ₦20,000
Reserved money:
₦170,000
That leaves:
₦80,000
before considering your normal daily expenses.
Step 3: Estimate Essential Spending Until Your Next Income
This is where many people make mistakes.
They remember large bills but forget regular expenses.
Consider the money you may need for:
- Food
- Transportation
- Airtime
- Data
- Household necessities
- Work-related expenses
You don’t need perfect predictions.
A reasonable estimate is better than ignoring these expenses completely.
Step 4: Create Your “Safe-to-Spend” Number
Now subtract your reserved money and expected essential expenses.
For example:
Bank balance: ₦250,000
Reserved money: ₦170,000
Essential spending estimate: ₦45,000
Safe-to-spend amount: ₦35,000
Now you have a much clearer picture.
You might still have ₦250,000 displayed by your banking app, but spending ₦100,000 would probably interfere with money that already has a purpose.
Don’t Confuse “Safe to Spend” With “Free Money”
Even your safe-to-spend amount should be handled carefully.
Suppose your calculation gives you:
₦35,000
That does not mean you must spend ₦35,000.
It simply means that amount has not currently been assigned to known obligations under your plan.
Keeping part of it available can provide additional flexibility.
The 48-Hour Purchase Test
Before making a significant non-essential purchase, try a simple test.
Ask yourself:
If I wait 48 hours, will I still want this?
If yes, ask:
Can I pay for it without touching reserved money?
Then ask:
Will buying it make my next important payment difficult?
If the answer to the last question is yes, postpone the purchase.
This is not about refusing every enjoyable purchase.
It is about preventing today’s decision from creating tomorrow’s financial problem.
A Nigerian Example
Imagine a worker receives ₦300,000.
The person sees ₦300,000 in the account and considers buying a ₦90,000 smartphone.
Before purchasing, they make a quick money map:
| Purpose | Amount |
|---|---|
| Current balance | ₦300,000 |
| Rent allocation | ₦100,000 |
| Food & transport | ₦50,000 |
| Other bills | ₦30,000 |
| Savings | ₦40,000 |
| Remaining flexible money | ₦80,000 |
The phone costs ₦90,000.
Although the account contains ₦300,000, the purchase exceeds the person’s planned flexible balance by ₦10,000.
The better question is therefore not:
“Do I have ₦90,000?”
It is:
“Can I spend ₦90,000 without taking money away from something important?”
That is the difference between looking at a bank balance and actually managing money.
Use Separate Money Purposes
One way to make this easier is to separate money according to purpose.
You can think in terms of:
Spending
Money for everyday expenses.
Bills
Money that will be needed for known obligations.
Savings
Money being kept for future goals or emergencies.
Business
If applicable, money needed to operate your business.
You do not necessarily need four separate bank accounts.
The important thing is that you know which money has already been committed.
Keep Business and Personal Money Organized
If you operate a small business, mixing business money with personal spending can make your bank balance particularly misleading.
For example, a trader may receive ₦500,000 in customer payments.
That does not mean the trader has ₦500,000 available for personal use.
Some of that money may be needed to:
- Restock goods
- Pay suppliers
- Cover transportation
- Pay workers
- Handle business expenses
A separate business account or clearly separated record of business money can make financial tracking easier.
Check Your Balance Before Major Spending
Make it a habit to check your finances before significant purchases.
You don’t need to do a full monthly budget every time.
A quick check can be enough:
Current balance: ₦______
Reserved money: ₦______
Upcoming essential expenses: ₦______
Planned savings: ₦______
Estimated flexible balance: ₦______
Purchase price: ₦______
Then ask:
“Will this purchase affect anything important?”
Watch Out for Pending Transactions
Your displayed balance may not always tell the complete story of your recent spending.
Depending on your bank and transaction type, some payments or transactions may still be processing.
Before making a large purchase, review your recent transactions and consider any payments you have already initiated.
This is especially useful if you frequently make transfers or card payments.
Don’t Forget Small Expenses
A person may correctly reserve ₦100,000 for rent but forget that dozens of smaller transactions can consume another significant amount.
Examples:
- Frequent food deliveries
- Small transfers
- Repeated airtime purchases
- Unplanned subscriptions
- Transport expenses
- Impulse shopping
This is why reviewing your transaction history is important.
Your Bank Balance Can Be High While Your Finances Are Tight
This sounds contradictory, but it happens frequently.
Someone may have:
₦500,000 in their account
while most of the money is already committed.
Another person may have:
₦80,000
but only ₦20,000 is committed to upcoming expenses.
The second person could actually have more flexibility than the first.
This is why cash balance and financial availability are not always the same thing.
A 5-Minute Weekly Money Check
Once a week, ask yourself:
1. What is my current balance?
₦__________
2. What money is already committed?
₦__________
3. What expenses are coming before my next income?
₦__________
4. How much have I saved?
₦__________
5. What amount can I safely spend?
₦__________
This simple routine can help you catch problems before they become serious.
What If Your Income Is Irregular?
If you are a freelancer, trader, farmer, commission worker or small-business owner, your income may not arrive on the same date every month.
In that situation, be particularly careful about treating your current balance as disposable income.
Instead, whenever money arrives, consider your upcoming needs first.
For example:
Money received: ₦70,000
Before spending it, ask:
- What must I pay?
- What do I need until my next income?
- How much should I save?
- What can safely remain available?
This approach can help prevent a good-income day from turning into a difficult week later.
Connect This With Your Savings Plan
Your savings should have a clear purpose.
You may be saving for:
- Emergency expenses
- Education
- Business capital
- A major purchase
- A future financial goal
If you repeatedly spend your savings on everyday expenses, your savings system may need to be redesigned.
See our guide on how to save money in a bank account in Nigeria.
Don’t Let a Large Balance Encourage Lifestyle Inflation
When income increases, spending often increases too.
For example, someone who previously earned ₦150,000 may start earning ₦250,000 and immediately increase spending because the new bank balance looks much larger.
Instead, consider giving part of the additional income a purpose.
For example:
- Increase savings
- Build an emergency reserve
- Invest after proper research
- Improve necessary expenses
- Strengthen your business
Higher income can create an opportunity to improve your financial position rather than simply increasing consumption.
Common Mistakes
Mistake 1: Spending based only on the displayed balance
Your account balance doesn’t show your complete financial plan.
Mistake 2: Forgetting upcoming expenses
A payment due next week is still your responsibility even if the money is currently sitting in your account.
Mistake 3: Treating savings as spending money
Savings should have a defined purpose.
Mistake 4: Ignoring small transactions
Small repeated expenses can gradually reduce your available money.
Mistake 5: Mixing business and personal funds
This can make it difficult to know what money actually belongs to you personally.
Frequently Asked Questions
What is the difference between bank balance and spendable balance?
Your bank balance is the amount shown in your account. Your spendable balance is the amount you can reasonably use after considering money already reserved for obligations, savings and essential upcoming expenses.
Should I spend all the money left after paying my bills?
Not necessarily. Some of the remaining money can be kept as a buffer or directed toward savings and future goals.
Can this method work with one bank account?
Yes. You can organize money by purpose even if you use one account. Some people may prefer separate accounts or savings arrangements if that makes their money easier to manage.
How often should I calculate my spendable balance?
A weekly check is a good starting point, and you can perform an additional check whenever you receive significant income or prepare for a major purchase.
Is a high bank balance a sign that I am financially healthy?
Not necessarily. A high balance can include money already committed to bills, business expenses or other obligations. Financial health depends on the broader picture.
Final Thoughts
Your bank balance is a number.
Your financial plan gives that number meaning.
The next time your banking app shows a large balance, don’t immediately assume that all of it is available for spending.
Separate what you have from what you have already promised to spend.
Once you start thinking in terms of reserved money, essential expenses and safe-to-spend money, your bank account can become a much more useful tool for managing your finances.
Related Guides on NaijaMoneyGuide
- How to Organize Your Bank Account for Better Money Management
- How to Save Money in a Bank Account in Nigeria
- Bank Account Charges in Nigeria
- How to Choose the Best Savings Account in Nigeria
Disclaimer
This article is provided for general financial education and information. It is not financial, investment, banking or legal advice. Individual financial circumstances differ, and readers should consider their own situation and verify relevant banking information with their financial institution before making important financial decisions.