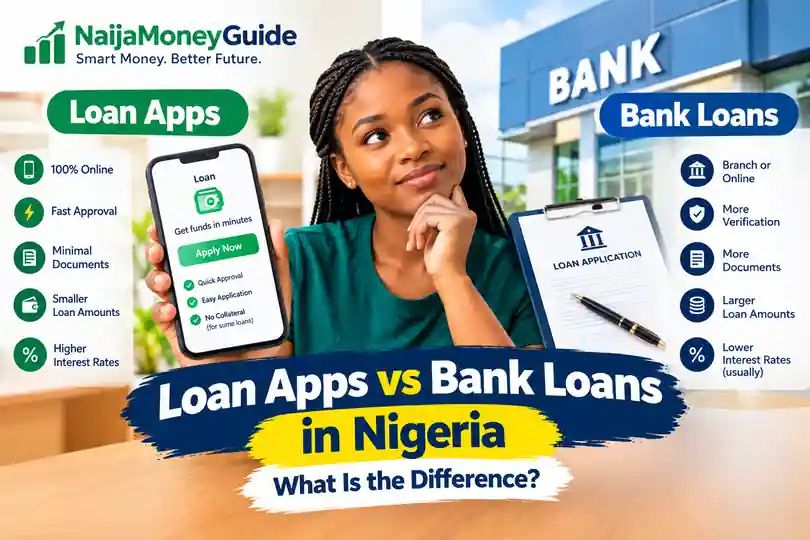
Loan apps and bank loans can both provide access to credit, but they usually differ in application process, eligibility requirements, loan size, repayment structure, documentation and customer support.
Loan apps may allow eligible customers to apply digitally with fewer physical documents, while bank loans may involve more formal eligibility checks and documentation. However, neither option is automatically cheaper or more suitable for everyone.
Before borrowing, compare the total amount you will repay, interest, fees, repayment period, penalties, automatic-debit terms and other conditions rather than choosing based only on how quickly you can receive the money.
What Is a Loan App?
A loan app is a digital platform that allows eligible customers to apply for or manage loans using a smartphone or other digital device.
Depending on the provider, the application process may involve identity verification, BVN-related checks, transaction information, credit assessment and other eligibility checks.
Some digital lenders operate independently, while others are connected to financial institutions or other regulated businesses.
The exact requirements, loan amount, interest and repayment terms vary from one provider to another.
What Is a Bank Loan?
A bank loan is credit provided by a commercial bank or another financial institution under an agreed lending arrangement.
Banks offer different types of loans, including:
- Personal loans
- Salary loans
- Business loans
- Asset-financing loans
- Mortgage loans
- Education-related financing
- Agricultural financing
- Overdrafts
- Working-capital facilities
The requirements can vary significantly depending on the loan product.
For example, a salary-based loan may depend on income and employment information, while a business facility may require information about business operations, cash flow or other supporting documents.
Loan Apps vs Bank Loans: Key Differences
1. Application Process
One of the biggest differences is how you apply.
Many loan apps allow users to complete the application through a smartphone without visiting a physical branch.
A bank may also offer digital applications, but some products can require additional documentation, verification or interaction with the bank.
Important: A digital application does not automatically mean that the loan is easier, cheaper or safer. Always check the lender and the actual loan terms.
2. Documentation Requirements
Loan apps may request information electronically, such as:
- Full name
- Phone number
- Bank details
- BVN
- Identification information
- Employment or income information
- Transaction-related information
Banks may request additional documentation depending on the product.
This can include:
- Proof of income
- Salary account information
- Bank statements
- Employment information
- Business documents
- Identification documents
- Collateral documents where applicable
The actual requirements depend on the lender and loan product.
3. Loan Amount
The amount available through a loan app or bank depends on the specific product and the borrower’s eligibility.
Some digital lenders provide relatively small short-term loans, while others may advertise larger amounts for eligible customers.
Banks can offer substantially larger facilities for certain personal, business, asset-financing or other loan products.
However, the maximum advertised amount is not the same as the amount every applicant will receive.
A lender may consider income, transaction history, repayment history, credit assessment, existing obligations and other eligibility criteria.
4. Speed of Access
Loan apps are often designed around digital applications, which can make the application process convenient.
Some providers may provide decisions quickly after the required information has been submitted.
Bank loan processing times vary. Some digital bank products can be processed quickly, while loans requiring detailed documentation, verification or collateral assessment can take longer.
Therefore, don’t judge a loan only by how quickly the money is available.
A fast loan can still be expensive if the total repayment is high.
5. Interest and Other Fees
This is one of the most important areas to compare.
A lender may charge interest as well as other applicable fees.
Possible costs can include:
- Interest
- Management fees
- Processing fees
- Insurance-related charges
- Late-payment charges
- Rollover charges
- Other disclosed costs
The exact charges vary by lender and product.
For digital consumer lending, the FCCPC’s 2025 DEON Consumer Lending Regulations require lending terms, including interest rates, repayment terms and associated fees, to be disclosed before a transaction is completed. The regulations also require lending information and charges to be presented clearly and not misleadingly.
Never compare loans using interest alone.
Instead, ask:
How much will I receive?
How much will I repay in total?
When must I repay it?
What happens if I pay late?
This gives you a better picture of the actual cost.
6. Repayment Period
Loan apps may offer short repayment periods, although some products provide longer terms.
Bank loans can also range from short-term facilities to loans lasting several years, depending on the product.
A longer repayment period can reduce the amount paid at each installment, but it may also increase the total cost of borrowing.
For example, consider a hypothetical loan:
- Amount borrowed: ₦500,000
- Total repayment: ₦600,000
- Repayment period: 6 months
The total cost of borrowing in this example is:
₦600,000 − ₦500,000 = ₦100,000
This is only an illustration. Actual loan costs depend on the lender and the specific offer.
7. Collateral Requirements
Some bank loans may require collateral, particularly larger facilities or specific types of business and asset financing.
Other bank products may be unsecured and depend on salary, account activity, credit assessment or other eligibility factors.
Some digital loans may also be unsecured.
However, “no collateral” does not mean “no conditions.”
An unsecured loan still creates a financial obligation that must be repaid according to the agreement.
8. Credit Assessment
Both digital lenders and banks can assess whether an applicant qualifies for a loan.
Depending on the product, the lender may consider factors such as:
- Income
- Existing debts
- Repayment history
- Account activity
- Transaction patterns
- Employment or business information
- Identity verification
- Credit information
- Other eligibility criteria
There is no universal formula used by every lender.
That means being approved by one provider does not guarantee approval from another.
9. What Happens If You Don’t Repay?
Failing to repay a loan can have financial consequences.
Depending on the loan agreement, these may include:
- Late-payment charges
- Additional interest or applicable fees
- Automatic debit attempts
- Collection activity
- Restrictions under the lender’s terms
- Possible impact on your credit profile
- Legal recovery actions where applicable
The exact consequences depend on the contract and applicable law.
The Central Bank of Nigeria’s consumer education materials state that bank customers have a responsibility to repay credit facilities and agreed interest when due and may face default charges when payments are delayed.
If you realize that you cannot make a payment, don’t simply ignore the lender.
Contact the lender as early as possible and ask about available repayment arrangements.
10. Customer Support and Complaints
Customer support is another important difference to consider.
Before accepting a loan, check:
- How to contact the lender
- Whether there is an official support channel
- Whether complaints can be submitted
- How disputes are handled
- Whether the lender provides a physical address or verifiable business information
Keep copies of:
- Loan agreements
- Repayment receipts
- Transaction records
- Emails
- SMS messages
- Screenshots of important loan terms
These records can become useful if there is a dispute.
For complaints involving financial institutions regulated by the CBN, the CBN advises consumers to first complain to the institution and follow its escalation process if the complaint is not resolved.
Loan Apps vs Bank Loans Comparison
| Feature | Loan Apps | Bank Loans |
|---|---|---|
| Application | Often digital | Digital or branch-based |
| Physical branch | Usually not required | May be available |
| Documentation | Varies | Varies by product |
| Processing | Some can be quick | Depends on product |
| Loan amount | Varies widely | Varies widely |
| Collateral | Depends on product | Depends on product |
| Repayment | Often digital | Digital, account-based or other methods |
| Interest | Varies | Varies |
| Fees | May apply | May apply |
| Customer support | App, phone, email or other channels | Branch, phone, app and other channels |
| Eligibility | Provider-specific | Product-specific |
| Approval | Not guaranteed | Not guaranteed |
Which One Should You Choose?
There is no single option that is suitable for every borrower.
Instead, compare the actual offer available to you.
A loan may appear attractive because it has:
- Fast processing
- Minimal paperwork
- A high advertised limit
- Easy digital application
But those features should not replace checking the actual financial cost.
Before accepting any loan, compare:
1. Amount received
How much money will actually enter your account?
2. Total repayment
How much will you pay back altogether?
3. Repayment frequency
Will you repay daily, weekly, monthly or according to another schedule?
4. Loan duration
How long do you have to repay?
5. Interest and fees
What charges are included?
6. Late-payment consequences
What happens if you miss a payment?
7. Automatic debit
Does the agreement authorize automatic deductions?
8. Data and privacy terms
What information does the lender collect and how does it use that information?
9. Lender information
Can you verify the company and the relevant regulatory status?
10. Affordability
Can you comfortably repay the loan without depending on another loan?
How to Calculate the Real Cost of a Loan
A simple starting calculation is:
Total Cost of Loan = Total Repayment − Amount Received
For example:
Suppose you receive:
₦300,000
And the total amount you must repay is:
₦360,000
Then:
₦360,000 − ₦300,000 = ₦60,000
Your financing cost in this simplified example is ₦60,000.
But you should also check whether there are separate fees or charges that affect the amount you actually receive.
5 Questions to Ask Before Taking a Loan
Before accepting any offer, ask:
1. How much money will I actually receive?
2. How much will I repay in total?
3. What is the exact repayment date or schedule?
4. What happens if I miss a payment?
5. Can my income comfortably cover the repayment without another loan?
If you cannot clearly answer these questions, don’t rush to accept the offer.
How to Avoid Loan Scams in Nigeria
Loan scams can use attractive advertisements to pressure people into sending money or personal information.
Be careful when a supposed lender:
- Guarantees approval for everyone
- Demands suspicious upfront payments before releasing a loan
- Hides the total repayment amount
- Uses unclear company information
- Pressures you to act immediately
- Requests unnecessary sensitive information
- Uses threatening or misleading advertisements
- Cannot clearly explain its terms and conditions
The FCCPC’s digital lending framework emphasizes transparent disclosure and states that lending advertisements should be factual, clear and not misleading or deceptive.
Also avoid downloading random loan APK files from unverified websites simply because they promise higher loan limits.
What to Do If You Already Have Too Many Loans
If you currently have several loans, consider stopping new borrowing until you understand your total obligations.
Create a simple list:
| Loan | Outstanding Amount | Due Date | Repayment |
|---|---|---|---|
| Loan 1 | ₦___ | ___ | ₦___ |
| Loan 2 | ₦___ | ___ | ₦___ |
| Loan 3 | ₦___ | ___ | ₦___ |
Then calculate your total outstanding debt.
This can help you see the situation clearly instead of taking another loan simply because a new offer is available.
If repayment is becoming difficult, contact the lenders and ask about available options rather than repeatedly borrowing to cover previous loans.
Frequently Asked Questions
Are loan apps cheaper than bank loans?
Not necessarily. The cost depends on the individual lender, product, interest, fees and repayment period. Compare the total repayment rather than assuming one category is cheaper.
Are bank loans safer than loan apps?
Safety depends on the specific provider, product, regulatory requirements, security practices and terms. Consumers should verify the lender and understand the agreement before borrowing.
Can I get a bank loan without collateral?
Some bank loan products do not require traditional collateral, while others do. Requirements depend on the specific product and your eligibility.
Can a loan app give me ₦1 million?
Some lenders advertise loan products above ₦1 million, but the amount offered to an individual depends on the provider’s eligibility and credit assessment. A maximum advertised limit is not a guarantee.
Does applying for several loans affect me?
Multiple applications and borrowing can increase your financial obligations and may affect how lenders assess your ability to repay. Avoid applying for loans simply to compare offers if you do not need the money.
What should I do if I cannot repay my loan?
Contact the lender as soon as possible, review your agreement and ask what repayment options are available. Do not ignore the obligation.
Should I borrow from one loan app to repay another?
Using new debt to repeatedly pay old debt can create a debt cycle. Before doing this, calculate your total obligations and consider whether there is a sustainable way to repay what you already owe.
Final Takeaway
Loan apps and bank loans both provide ways to access credit, but the differences go beyond application speed.
The most important things to compare are:
- Amount received
- Total repayment
- Interest and fees
- Repayment period
- Repayment frequency
- Late-payment consequences
- Automatic-debit terms
- Eligibility requirements
- Lender information and regulatory status
- Whether the repayment is affordable
A loan should fit your financial situation rather than simply being available to you.
Take time to read the agreement before accepting any offer, and never borrow more than you have a realistic plan to repay.
Related Articles on Naija Money Guide
- How to Get a Loan in Nigeria: A Complete Guide to Requirements, Options and What to Check Before Borrowing
- How to Identify Legitimate Loan Apps in Nigeria: 12 Things to Check Before Borrowing
- 10 Loan Apps and Digital Loan Platforms in Nigeria That Offer Loans Above ₦1 Million
- How to Get a ₦1 Million FairMoney Loan in Nigeria: Registration, Requirements and Step-by-Step Guide
Financial Disclaimer
This article is for general financial education and informational purposes only. Loan products, eligibility requirements, interest rates, fees, repayment periods and lender policies can change. Always confirm the current terms directly with the relevant lender before applying or accepting a loan.
Naija Money Guide does not guarantee loan approval and does not provide loans or financial services through this article. Readers should consider their own financial circumstances and seek qualified professional advice where necessary.