How to Get a Loan in Nigeria: Requirements & Guide
Getting a loan can help individuals and businesses manage important expenses, deal with temporary cash-flow problems or finance a productive project.
However, borrowing money is a financial commitment. Before applying for any loan in Nigeria, it is important to understand the lender, eligibility requirements, interest or other charges, repayment period, penalties and the total amount you will eventually repay.
This guide explains how loans work, the main borrowing options available in Nigeria, what lenders may require, how to compare loan offers and the precautions you should take before submitting your personal information.
Important: This article is for general financial education and does not guarantee loan approval or recommend that you borrow money. Loan availability, eligibility criteria, interest rates, fees and repayment terms vary between lenders and can change over time. Always confirm current terms directly with the relevant lender or regulator before making a financial decision.
What Is a Loan?
A loan is money or another form of financial value provided by a lender to a borrower with an agreement that it will be repaid according to specified terms.
Depending on the type of loan, repayment may include:
- The amount borrowed
- Interest or other financing charges
- Processing or administrative fees
- Applicable penalties or other charges
For example, if you borrow ₦200,000, the amount you repay may be higher than ₦200,000 depending on the lender’s pricing and the agreement you accept.
This is why borrowers should look beyond the amount they receive and understand the total cost of borrowing.
Types of Loans Available in Nigeria
There is no single loan that is suitable for everyone. Different types of loans serve different purposes.
1. Personal Loans
Personal loans are generally designed for individual financial needs.
Depending on the lender, they may be used for expenses such as:
- Household needs
- Emergency expenses
- Personal projects
- Education-related expenses
- Other permitted personal purposes
Eligibility requirements and repayment terms differ between lenders.
2. Business Loans
Business loans are designed to provide financing for business-related activities.
A small business may seek financing for:
- Buying inventory
- Purchasing equipment
- Expanding operations
- Working capital
- Business improvements
Some lenders may request evidence of business activity, transaction history, financial records or other documentation.
3. Salary or Employee Loans
Some financial institutions offer loan products to eligible employees.
The lender may consider factors such as:
- Monthly income
- Employer
- Salary history
- Existing obligations
- Bank account activity
- Repayment capacity
The exact requirements depend on the financial institution and loan product.
4. Agricultural Loans
Agricultural financing can support activities such as:
- Crop production
- Livestock farming
- Agricultural equipment
- Processing
- Storage
- Other agricultural activities
Some agricultural financing programmes may have specific eligibility conditions and application procedures.
5. Education Loans
Education financing can help eligible borrowers meet certain education-related expenses.
The requirements and repayment arrangements depend on the institution providing the financing.
6. Digital Loans
Digital lending allows consumers to apply for certain loan products through websites or mobile applications.
This can make applications more convenient, but convenience should not replace due diligence.
Before using a digital lender, verify who operates the service, understand the terms and check the applicable regulatory requirements.
Nigeria’s Federal Competition and Consumer Protection Commission introduced the Digital, Electronic, Online, or Non-traditional Consumer Lending Regulations 2025, covering applicable digital and online consumer lending activities in Nigeria.
What Do You Need to Apply for a Loan in Nigeria?
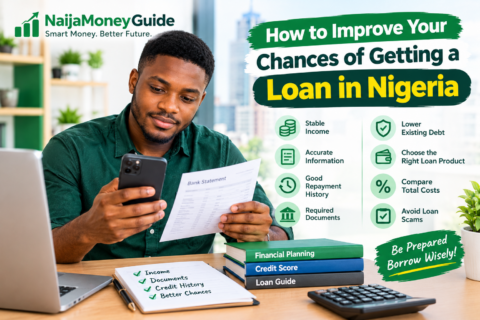
Requirements differ from one lender to another, so there is no universal checklist.
However, a lender may request some of the following:
Personal information
You may be asked for:
- Full name
- Date of birth
- Phone number
- Residential address
- Identification information
Income information
Depending on the loan, the lender may request:
- Salary information
- Employment details
- Bank statements
- Proof of income
- Business records
Identification documents
Some lenders may require an acceptable form of identification or other verification documents.
Bank account information
Depending on the product, your bank account may be used to assess affordability, disburse funds or collect repayments.
Never provide sensitive financial information to an unverified person or website simply because they promise fast approval.
How to Apply for a Loan in Nigeria
The application process depends on the lender, but the general process usually looks like this.
Step 1: Determine why you need the money
Before looking for a loan, clearly identify the purpose.
Ask yourself:
How much do I actually need?
Borrowing more than necessary can increase your repayment burden.
Step 2: Calculate what you can comfortably repay
Look at your regular income and essential expenses.
For example:
Monthly income − essential expenses − existing debt payments = approximate amount available for additional financial commitments
This is not a lender’s official affordability calculation, but it can help you think about whether another repayment would fit into your budget.
Step 3: Research potential lenders
Compare more than one option where possible.
Look at:
- Interest or financing cost
- Fees
- Repayment period
- Total repayment amount
- Late-payment consequences
- Eligibility requirements
- Complaint and customer-support channels
Do not select a loan simply because it advertises the largest amount.
Step 4: Verify the lender
This is one of the most important steps.
Check whether the lender is properly authorised or regulated for the type of financial service it provides.
The Central Bank of Nigeria’s consumer-protection guidance encourages consumers to carry out due diligence and deal with licensed financial institutions where applicable.
For digital lending businesses, also pay attention to the applicable consumer-lending regulatory framework.
Step 5: Read the loan agreement
Before accepting the loan, read the terms carefully.
Pay particular attention to:
- Amount you will receive
- Interest or financing charges
- Processing fees
- Repayment frequency
- Repayment dates
- Total amount payable
- Late-payment charges
- Early-repayment conditions
- Data/privacy provisions
- What happens if you miss a payment
Never accept an agreement you do not understand.
Step 6: Submit your application
Only provide information through the lender’s official application channel.
Avoid sending identity documents, passwords, PINs or financial credentials to unknown individuals through social media or messaging platforms.
Step 7: Review the final offer
Even after submitting an application, check the final offer before accepting it.
The amount offered may differ from what you initially expected.
Step 8: Keep records
Save:
- The loan agreement
- Repayment schedule
- Receipts
- Transaction references
- Customer-support communications
Keeping these records can make it easier to resolve a dispute if one occurs.
How to Compare Two Loan Offers
Suppose you receive two offers.
Loan A
- Amount: ₦200,000
- Repayment period: 6 months
- Total repayment: ₦230,000
Loan B
- Amount: ₦200,000
- Repayment period: 6 months
- Total repayment: ₦250,000
If all other conditions are genuinely comparable, Loan A has the lower stated total repayment.
But borrowers should not compare only one number.
Also consider:
- Whether additional fees apply
- Repayment dates
- Penalties
- Whether the quoted amount is the actual amount you receive
- Whether the terms can change
- What happens if you repay late
The cheapest-looking offer is not automatically the best option if its terms are less suitable for your circumstances.
What Is the Difference Between Interest and Fees?
This is an important distinction.
Interest is generally the cost charged for borrowing money.
Fees may cover other services or administrative activities associated with a financial product.
A loan could therefore have an interest charge as well as additional fees.
That is why you should look at the overall cost of the loan, rather than focusing only on a headline interest figure.
Google’s financial-services guidance emphasizes the importance of transparent information about costs and relevant loan terms when financial products are promoted.
What Happens If You Cannot Repay a Loan?
Failing to repay a loan can have financial consequences.
Depending on the agreement and applicable rules, consequences may include:
- Additional charges
- Collection activity
- Damage to your credit history
- Legal action in appropriate circumstances
- Difficulty accessing future credit
The exact consequences depend on the lender, contract and applicable Nigerian laws or regulations.
If you realise that you may miss a repayment, it is generally better to contact the lender through its official customer-service channel rather than ignoring the problem.
How to Avoid Loan Scams in Nigeria
Loan scams can take different forms.
Be particularly cautious when someone:
- Guarantees approval regardless of your circumstances
- Requests unusual upfront payments before a supposed loan
- Claims to represent a bank or government programme without verifiable evidence
- Requests your PIN or password
- Asks you to send sensitive information through an unverified account
- Uses pressure or threats to make you act immediately
- Promises unusually large amounts with unrealistic conditions
A legitimate financial offer should be independently verifiable.
Google’s publisher policies prohibit deceptive practices and misleading financial claims, including false or unrealistic financial promises.
Should You Borrow From a Loan App?
A loan app may be convenient, but convenience should not be the only consideration.
Before using one, check:
- Who owns and operates the service?
- What regulatory requirements apply?
- How much will you receive?
- How much will you repay?
- What are the fees?
- When is repayment due?
- What happens if you pay late?
- What information does the application request?
- How can you contact customer support?
- Is the information provided in the agreement clear?
If you cannot determine the total repayment cost before accepting the loan, consider that a warning sign.
Should You Take a Loan to Pay Another Loan?
This requires particular caution.
Taking a new loan to repay an existing loan can sometimes increase your overall debt rather than solve the underlying problem.
Before doing this, calculate:
- Existing outstanding balance
- New loan amount
- New fees
- New interest or financing cost
- New repayment period
- Total amount you will eventually pay
If the new arrangement simply moves the debt forward while increasing the total cost, it may create a larger financial burden.
Alternatives to Taking a Loan
Borrowing is not always the only option.
Depending on your situation, alternatives may include:
Building an emergency fund
Regularly setting aside a small amount can provide a buffer for unexpected expenses.
Reducing non-essential spending
Temporarily reducing discretionary expenses may help you meet a short-term financial need without borrowing.
Increasing income
A side business, freelance work or additional legitimate income source may sometimes be more appropriate than taking on new debt.
Negotiating payment terms
For certain bills or obligations, you may be able to discuss alternative payment arrangements directly with the provider.
Exploring legitimate grants or support programmes
Some government, nonprofit or private-sector programmes may provide grants or other forms of support to eligible applicants.
However, always verify that a grant programme actually exists before submitting personal information or paying any supposed application fee.
Frequently Asked Questions
Can anyone get a loan in Nigeria?
No. Loan approval is not guaranteed. Each lender establishes its own eligibility requirements and assessment process.
Can I get a loan without collateral?
Some loan products may not require traditional physical collateral, but this does not mean approval is guaranteed. The lender may use other eligibility and risk-assessment criteria.
How much can I borrow?
There is no universal amount. The maximum available depends on the lender, product, applicant’s circumstances and other factors.
Is every loan app in Nigeria legitimate?
No. Consumers should independently verify a digital lender and understand the applicable regulatory requirements before borrowing.
Does applying for several loans guarantee approval?
No. Submitting multiple applications does not guarantee approval and could increase your financial risk if you eventually accept more debt than you can comfortably repay.
What should I do if I think a loan company is treating me unfairly?
Keep your agreement and transaction records and use the lender’s official complaint channel first. Where appropriate, consumers can also seek assistance through the relevant regulator or consumer-protection mechanism.
For more information: How to Identify Legitimate Loan Apps in Nigeria
Final Thoughts
Getting a loan in Nigeria can be useful for a genuine financial need, but borrowing should be approached carefully.
The most important questions are not simply “How much can I get?” or “How quickly can I get it?”
Instead, ask:
How much will I repay in total?
Can I comfortably afford the repayments?
Who is providing the loan?
Are the terms clear?
What happens if I cannot repay on time?
Taking time to answer these questions can help you make a more informed financial decision and avoid unnecessary debt.
At Naija Money Guide, our goal is to provide practical and easy-to-understand financial information for Nigerians. Loan terms, regulations, eligibility requirements and available programmes can change, so readers should always confirm current information with the relevant official provider or regulator before taking action.
Financial Disclaimer
This article is provided for general educational and informational purposes only. Naija Money Guide is not a bank, lender, financial institution, loan broker or government agency, and this article does not constitute a loan offer, financial advice or a guarantee of approval. Loan products, interest rates, fees, eligibility requirements and regulations may change. Always conduct your own research and confirm current terms directly with the relevant licensed or authorised provider before borrowing money.